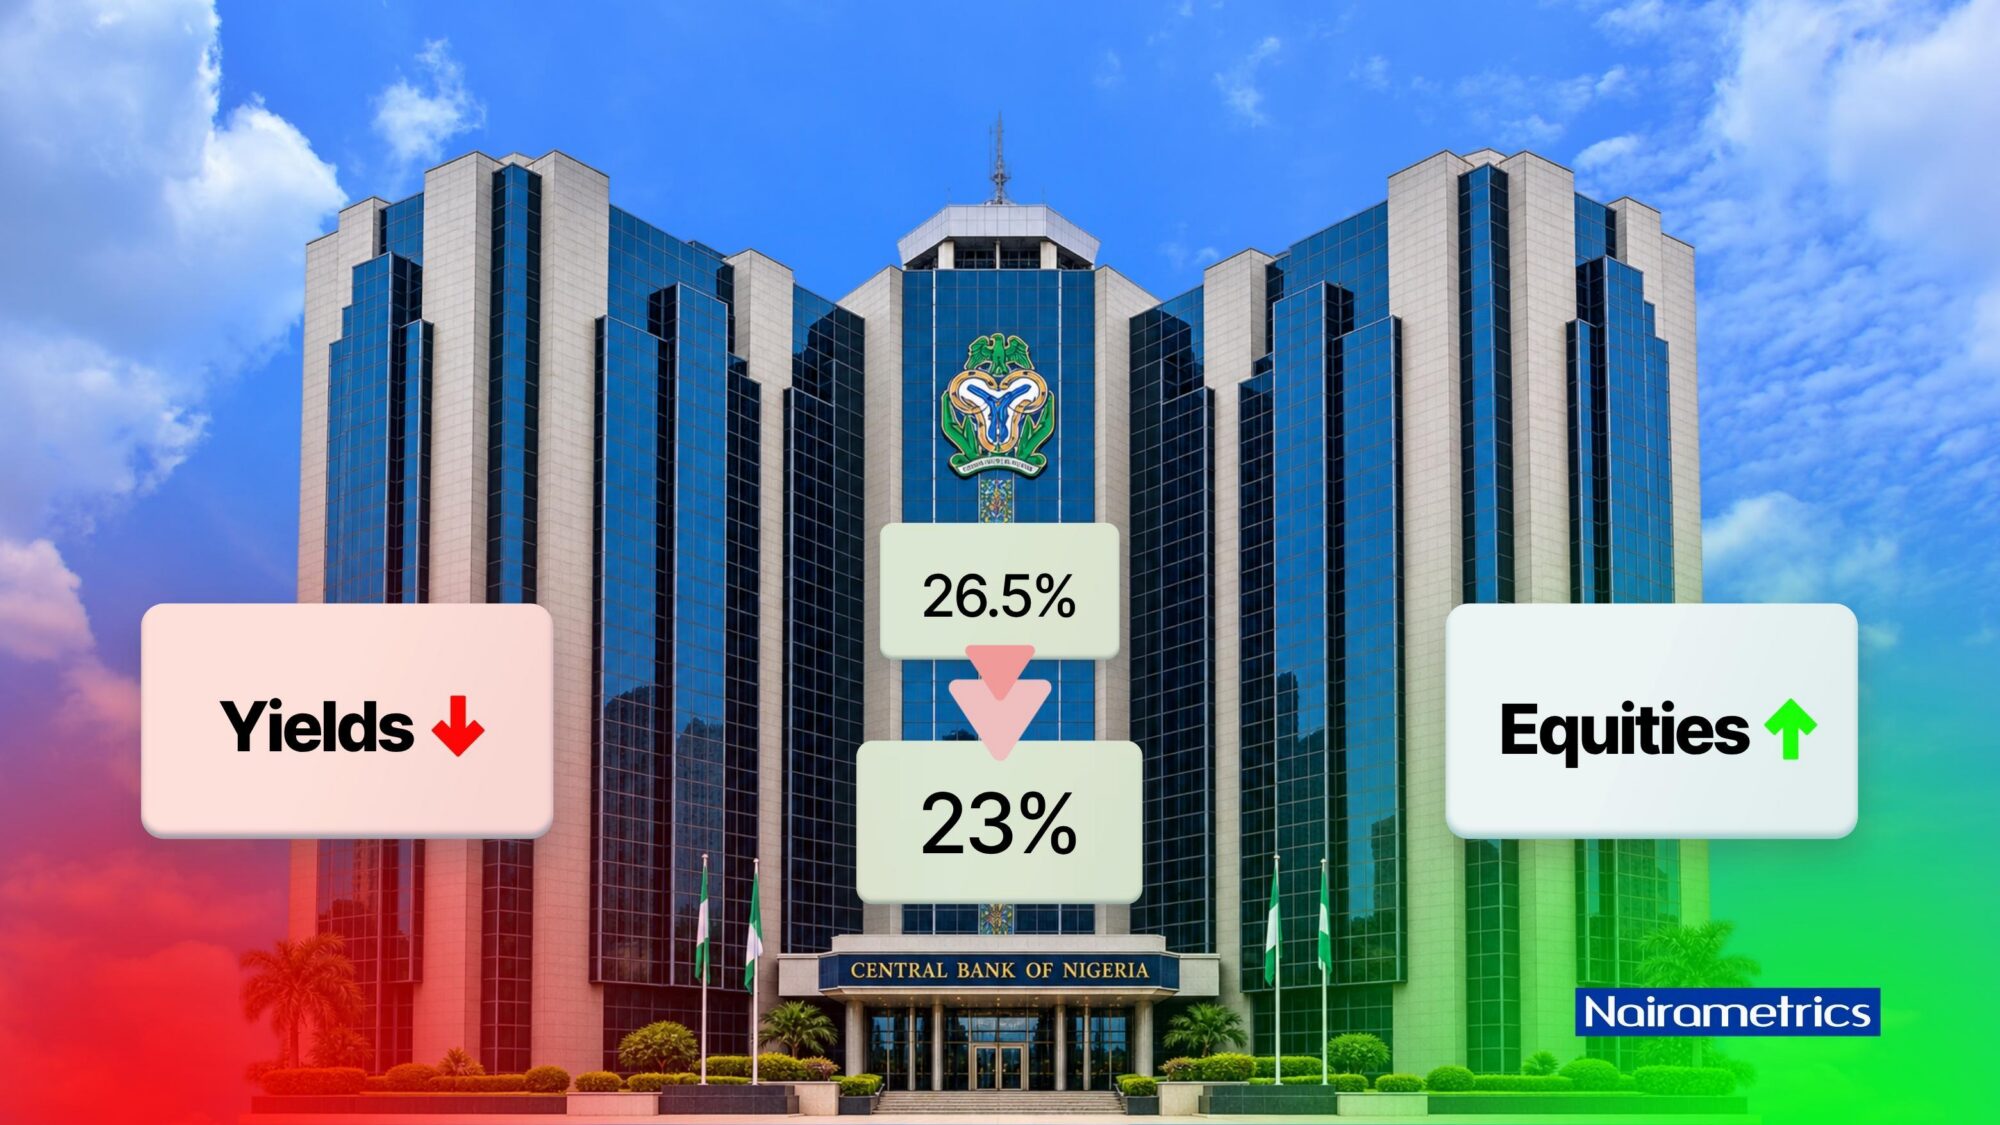
The Central Bank of Nigeria’s decision to cut the Monetary Policy Rate by 350 basis points to 23% could reshape how investors allocate money across fixed income and equities, although stockbrokers expect the benefits to vary across sectors and companies.
The Monetary Policy Committee reduced the MPR from 26.5% to 23% at its September meeting and reset the standing facilities corridor to +50/-300 basis points.
This places the Standing Lending Facility at 23.5% and the Standing Deposit Facility at 20%, while the Cash Reserve Requirement for Deposit Money Banks was retained at 45%.
CBN Governor Olayemi Cardoso described the recalibration of the corridor as an operational reset aimed at improving monetary policy transmission rather than signaling a separate change in policy stance.
For investors, however, a 350-basis-point reduction in the benchmark rate remains significant.
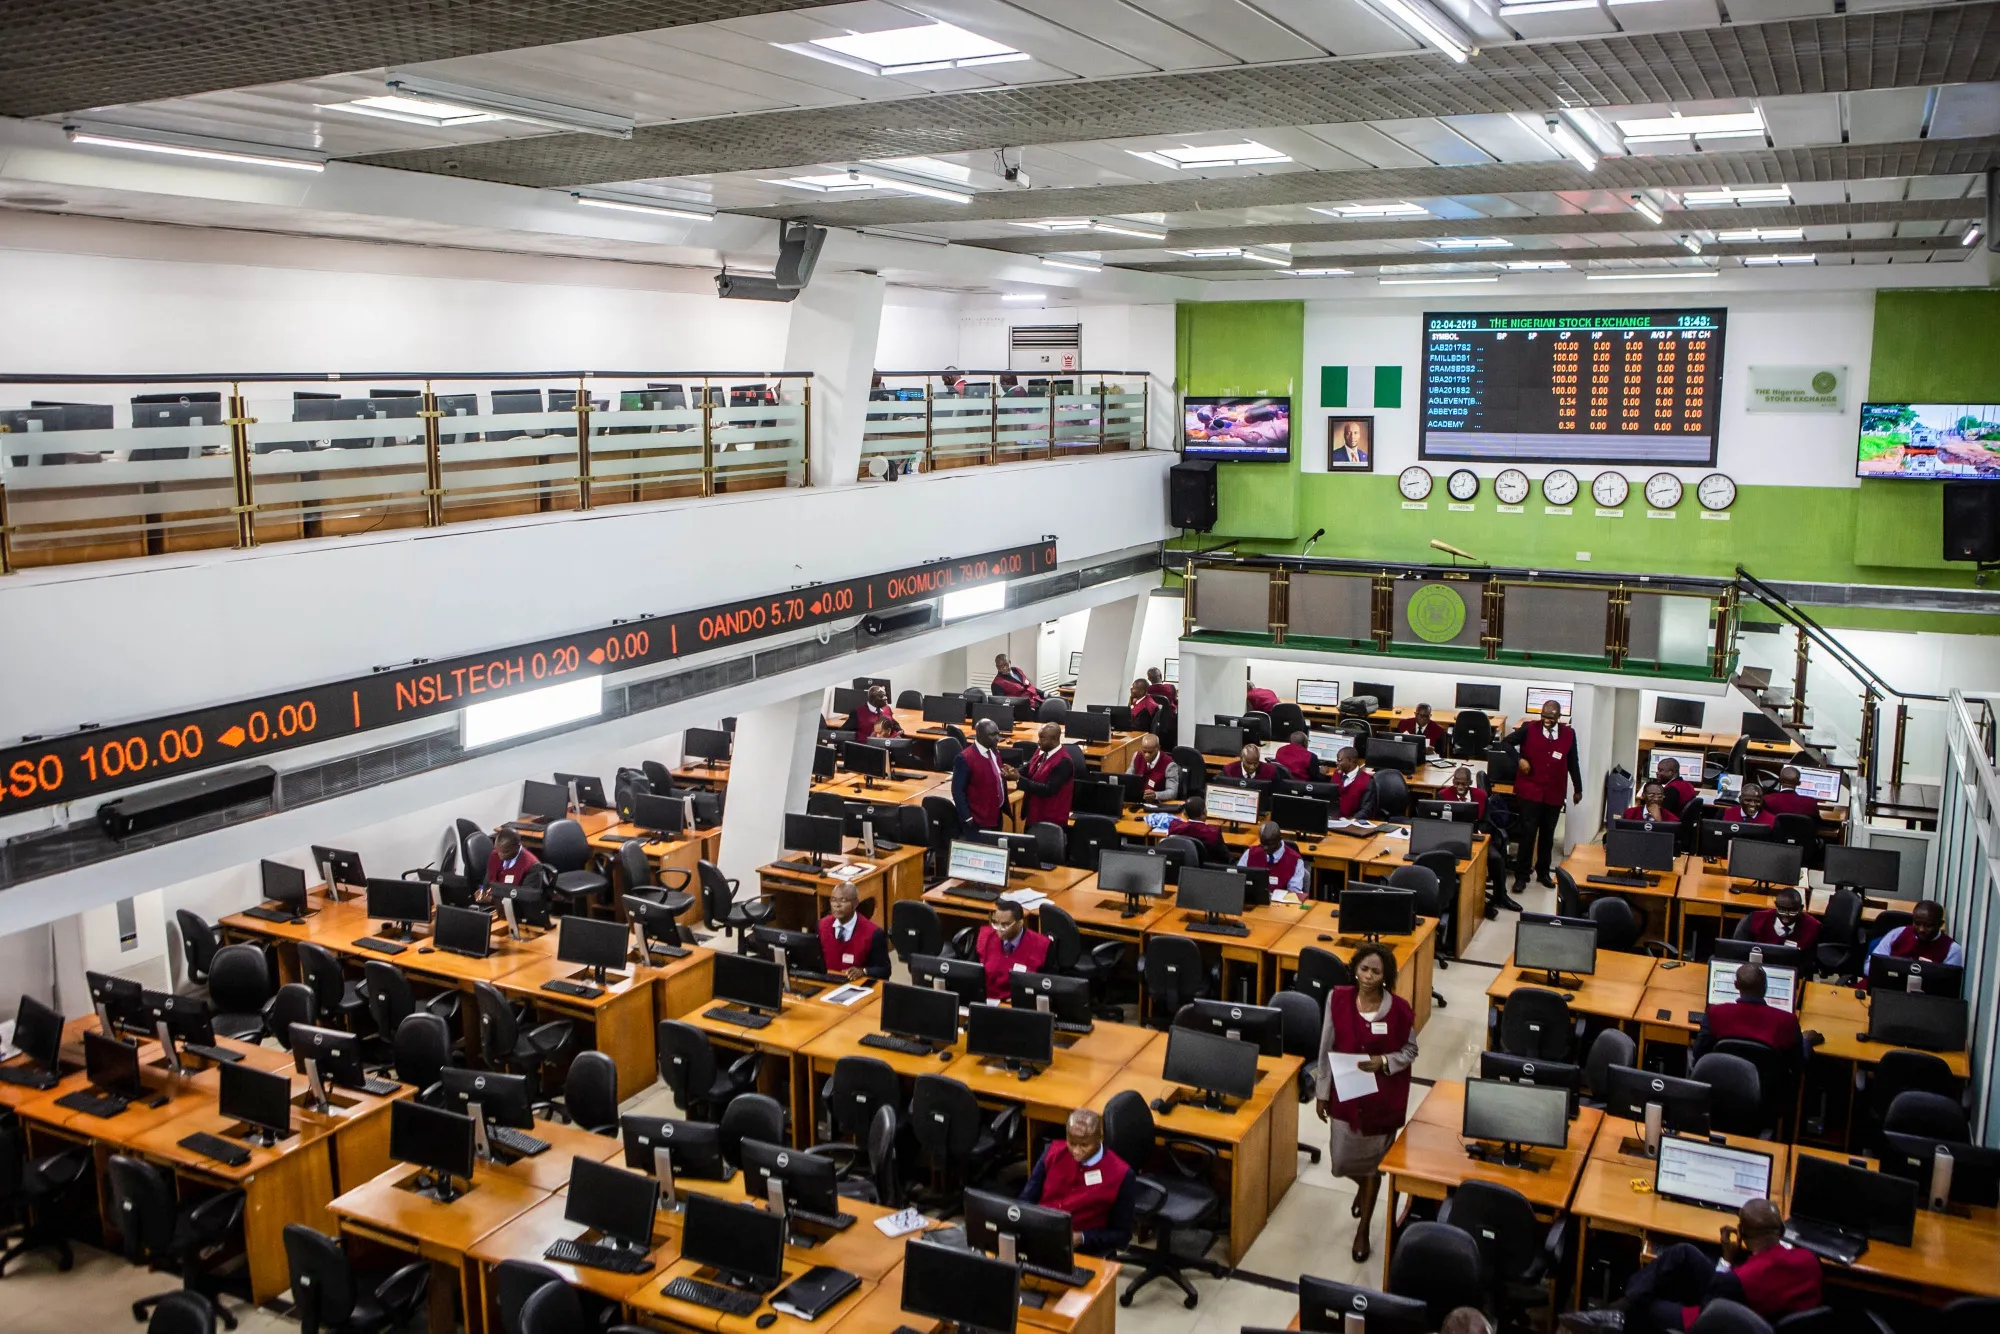
It comes at a time when Treasury bill yields have already been declining, with the 364-day stop rate falling to 16.62% in September, its third consecutive decline, while the Nigerian equities market has gained more than 60% year-to-date.
The question now is what the lower-rate environment means for investors’ money.
The most immediate impact may be felt in Treasury bills, bonds, and other fixed-income instruments, where yields were already declining before the MPC decision.
The 364-day Treasury bill rate fell from 17.59% in August to 16.62% by September 9, marking three consecutive cuts and a decline of nearly one percentage point in about a month.
Futureview Securities expects the trend to continue, although it believes market yields may not decline by the full 350 basis points because rates had already moved below the previous MPR.
For investors entering the fixed-income market, this could mean accepting lower returns on newly issued securities as yields adjust.
Existing holders of longer-dated bonds could experience the opposite effect. When market yields fall, bonds issued earlier at higher interest rates generally become more attractive, potentially supporting their prices in the secondary market.
But how far yields fall will also influence whether investors begin shifting more aggressively into equities.
Vincent Oshoma, Head of Business Development at Blue Marina Securities, said the pace of adjustment in Treasury bill and bond yields will be critical to investor flows.
Futureview Securities expects declining fixed income yields to improve the relative attractiveness of equities but does not see the rate cut as a reason for investors to buy the market indiscriminately.
With the NGX already up more than 60% this year, the firm expects earnings, dividends, valuations and company-specific fundamentals to increasingly determine which stocks outperform.
Among banks, Futureview highlighted Zenith Bank, GTCO, UBA, Stanbic IBTC and Access Holdings as potential beneficiaries of stronger credit demand, although lower market yields could pressure treasury income and net interest margins.
The argument that the rally could become more selective is reinforced by First Securities Brokers Limited, which approaches the impact partly from a valuation perspective.
Isaac Valentine Osaro, Head of Research at First Securities Brokers Limited, said lower rates could increase the value investors place on companies’ future cash flows.
But he does not expect this to translate into gains across the entire market.
In effect, both firms see room for fixed-income-to-equity rotation, but with the market already around record levels, where the money goes may become more important than the rotation itself.
For banks, the impact is more nuanced because lower rates affect both the returns earned on surplus liquidity and the cost of short-term funding.
With the Standing Deposit Facility now at 20%, compared with about 22% under the previous framework, banks earn less on excess funds placed with the CBN.
At the same time, the Standing Lending Facility has fallen to 23.5% from 27%, reducing the cost of accessing short-term liquidity from the apex bank.
In his view, this could give banks an incentive, at the margin, to seek better returns through lending and other investments, particularly if fixed-income yields continue to moderate.
But lower rates could also create pressure on earnings.
First Securities see another potential benefit through asset quality. Osaro said lower rates could reduce borrowers’ debt-servicing burden, improving their ability to repay loans.
Over time, First Securities expects this to reduce the formation of new non-performing loans, slow the migration of exposures into Stage 2 and Stage 3 and potentially lower banks’ expected credit losses and cost of risk.
The key question is how quickly the rate cut filters into the real economy.
Lower policy rates do not automatically translate into cheaper loans, so investors should watch Treasury bill and bond yields, bank lending and deposit rates, the naira, and domestic and foreign portfolio flows for signs of broader transmission.
If fixed-income returns continue to fall, equities could become relatively more attractive. But with the market already up strongly, the focus is likely to shift from simply buying stocks to identifying companies that can turn lower financing costs into stronger earnings and cash flow.
The rate cut may provide the catalyst, but earnings quality, balance-sheet strength and valuation are likely to determine the eventual winners.