Nigeria’s macroeconomic indicators have begun to show signs of stabilisation, with stronger GDP growth, moderating inflation, improved manufacturing output and a period of greater exchange-rate stability.
However, the improvement in headline indicators has yet to fully ease the pressures facing businesses on the factory floor.
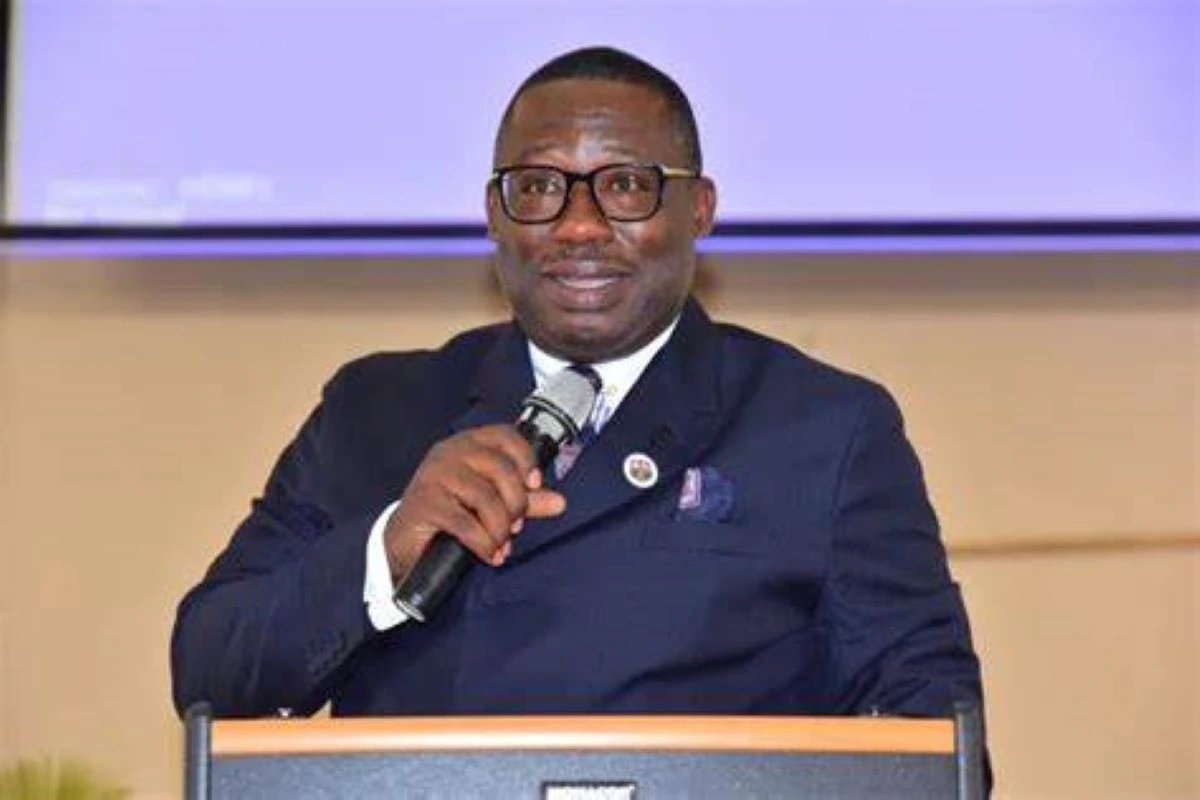
In an interview with Nairametrics, Hon. Dele Kelvin Oye, Chairman of Alliance for Economic Research and Ethics Ltd/GTE, said the government’s reforms have helped rebuild the macroeconomic foundation, but manufacturers continue to contend with high energy, financing, logistics, tax and input costs.
Oye said the next phase of the reform programme should focus on translating macroeconomic gains into lower production costs, stronger productivity and improved competitiveness for Nigerian manufacturers.
Oye: The honest answer is that Nigeria has moved from emergency surgery to rehabilitation. That is progress—but rehabilitation is not the same as running a marathon. The patient is alive, the vital signs are improving, and the doctors deserve credit; but the hospital bill is still arguing with the family.
The reforms have begun to restore important foundations. Nigeria has pursued foreign-exchange-market reforms, removed petrol subsidies, and introduced a consolidated tax framework effective from 1 January 2026.
The macroeconomic numbers are no longer merely a collection of bad headlines: real GDP grew by 4.43% in Q2 2026, real manufacturing output grew by 3.24%, inflation fell to 15.43% in July, and the August PMI reading of 54.3 indicated expansion in private-sector conditions.
But macroeconomic stabilisation is not yet the same as industrial comfort. The CBN’s official NFEM series should be read by date, not by political slogan. It showed the naira at N1,315.67 per US dollar on 3rd September 2026, but it would be inaccurate to claim that the currency remained continuously below N1,400 throughout the year. Manufacturers remember the periods of volatility because they purchased machinery, raw materials and spare parts at those prices.
A manufacturer in Onitsha does not eat GDP growth for breakfast. The factory pays diesel, electricity, wages, transport, taxes, interest and foreign-exchange costs. My conclusion is therefore neither cynical nor celebratory: the reform direction is improving the macroeconomic platform, but the transmission to the factory floor remains incomplete. Government must now turn stabilisation into productivity.
Oye: The most serious threat is not one cost in isolation; it is the compound cost of doing business in an economy where every burden arrives with a friend. Energy brings logistics. Logistics brings working-capital pressure. Working-capital pressure brings expensive credit. Expensive credit reduces investment, and weak investment keeps productivity low. The circle then returns to the factory like an unpaid debt collector.
The fuel figures require precision. NBS reported an average petrol price of N1,596.25 per litre in May 2026. A 45-litre tank therefore cost N71,831.25—not an unsupported range of N71,800 to N79,800. That comparison is useful because the amount exceeded the N70,000 national minimum wage, but petrol is not the right proxy for the energy cost of most industrial self-generation. NBS reported average diesel at N3,277.47 per litre in the same month. That is the number that speaks more directly to many factories running generators.
The deeper problem is the margin squeeze. Producers face higher costs while consumers face lower real purchasing power. A manufacturer cannot pass every increase to the customer because the customer has also become an economist—he now calculates, postpones, substitutes and sometimes simply walks away. Nigeria’s falling inflation rate is welcome, but a slower increase in prices does not mean that the price level has returned to where it was.
If we want competitive industry, we must reduce the total burden, not merely celebrate one favourable statistic. The factory needs reliable power, stable rules, affordable credit, efficient transport and consumers whose purchasing power can meet the products that industry makes.
Oye: Nigeria can begin industrialisation before solving every energy problem, but it cannot achieve broad, durable and globally competitive industrialisation while manufacturers remain forced to build private power systems merely to keep their machines awake.
The argument should not be exaggerated into saying that industrialisation is mathematically impossible. Nigerians are too inventive to accept that verdict. The stronger argument is that unreliable power taxes every unit produced. It raises the cost of production, interrupts schedules, damages equipment, increases maintenance, and makes long-term planning look like fortune-telling.
NERC’s tariffs are not one national figure; they vary by customer class, distribution company and tariff order. The September 2026 order cited for the relevant Band A category lists N209.50 per kWh, so N225 should not be reported as a universal national rate.
Diesel generation is even more punishing when tested against NBS’s May 2026 average diesel price of N3,277.47 per litre, although the exact cost per kilowatt-hour depends on generator efficiency, load factor, maintenance and utilisation.
Nigeria’s gas endowment offers genuine hope. NUPRC reported 2P (proved and probable) natural-gas reserves of 215.19 trillion cubic feet as of 1 January 2026. But gas beneath the ground is not yet electricity in a factory. The missing links are reliable gathering, processing, transmission, distribution, payment discipline, and infrastructure maintenance.
The Dangote Refinery is an important industrial development, and its official product page confirms gasoline, diesel, aviation fuel and polypropylene among its products. However, claims about 650,000-barrel-per-day capacity, a 700,000-barrel expansion, 60% or 90% coverage of domestic demand, or a precise annual import-substitution saving should not be presented as settled facts without a dated company or regulator source.
The national lesson is simple: a refinery can improve fuel security, but it cannot replace a functioning power system. You cannot power a twenty-first-century factory with promises, however well-refined.
Oye: Exchange-rate stability is a necessary condition for lower costs, but it is not an automatic discount coupon. The CBN’s official series should be cited by date and rate; on 3rd September 2026, the NFEM rate displayed was N1,315.67 per US dollar. That is useful evidence of a calmer market, not a guarantee that every price tag will immediately follow.
There are several reasons. Importers may still hold inventory acquired at an earlier, weaker exchange rate. Supplier contracts may have been priced under previous conditions. Freight, port charges, transport, electricity, and diesel may remain high. A local supplier may still be recovering the cost of imported inputs. A manufacturer may also use a period of currency stability to repair a balance sheet damaged by the earlier shock rather than reduce prices immediately.
This is why I would not promise a six-to-twelve-month timetable. The responsible expectation is conditional: relief should become more visible if exchange-rate stability persists, foreign-exchange access improves, and energy, logistics and interest costs moderate together.
The consumer usually receives the benefit last. The manufacturer must first survive the old cost structure, replace depleted working capital and regain confidence before lower costs can travel through the supply chain. Stabilization is the bridge; productivity is what gets people to the other side.
Oye: Because Nigeria has often tried to build the skyscraper before finishing the foundation—and then blamed the building for refusing to stand.
Import substitution is not achieved by decree alone. You cannot improve production by legislative fiat. It requires reliable infrastructure, patient finance, technical skills, predictable regulation and functioning upstream industries.
Nigeria still imports many specialised chemicals, machines, components, tools and industrial materials. When electricity is uncertain, interest rates are high, ports and roads are slow, and policies change without adequate transition time, local production becomes expensive before it reaches efficient scale.
The textile example is powerful, but its historical numbers must be handled with intellectual discipline. Claims that Nigeria once had more than 180 mills and now has fewer than 25 operational mills appear in industry and media accounts, but definitions and counting periods differ. Those figures should not be presented as official statistics without a named and dated industry source.
There are, nevertheless, signs of a more promising industrial architecture. The Dangote Refinery’s official product information includes polypropylene, creating potential feedstock for plastics and related downstream manufacturing. But one major project cannot create an entire ecosystem. Nigeria needs linked value chains in petrochemicals, steel, packaging, machinery, agro-processing, textiles and industrial services.
A serious industrial policy must ask not only, “What can we produce?” It must also ask, “What inputs do we need to produce it, who will supply them, how will they move, and at what cost?” A factory is not an island. It is a citizen of an ecosystem.
Oye: Nigerian manufacturers are not afraid of competition. They are afraid of unfair competition wearing the respectable suit of free trade.
Protection can be useful when it is temporary, transparent, targeted and linked to measurable productivity improvements. It becomes dangerous when it shelters inefficiency indefinitely. But instant liberalisation can also be destructive when local producers face imported goods made in countries with cheaper power, cheaper credit, smoother logistics and more predictable policy.
The choice is therefore not between permanent protection and reckless exposure. The wiser path is strategic openness: support local industry while requiring better standards, deeper investment, technology transfer, job creation and export performance. Protection must be a bridge to competitiveness, not a permanent residence.
The tax regime belongs in this conversation. The Nigeria Tax Act, 2025, effective from 1st January 2026. The Act consolidates several legacy tax laws and introduces a credit-based Economic Development Tax Incentive framework in place of the former Pioneer Status structure, subject to statutory conditions.
That reform may improve clarity, but tax clarity alone cannot make an uncompetitive factory competitive. Industry needs a whole operating environment in which taxes, power, finance, customs and standards work together. A country cannot tax its way into productivity, just as it cannot subsidise its way into excellence forever.