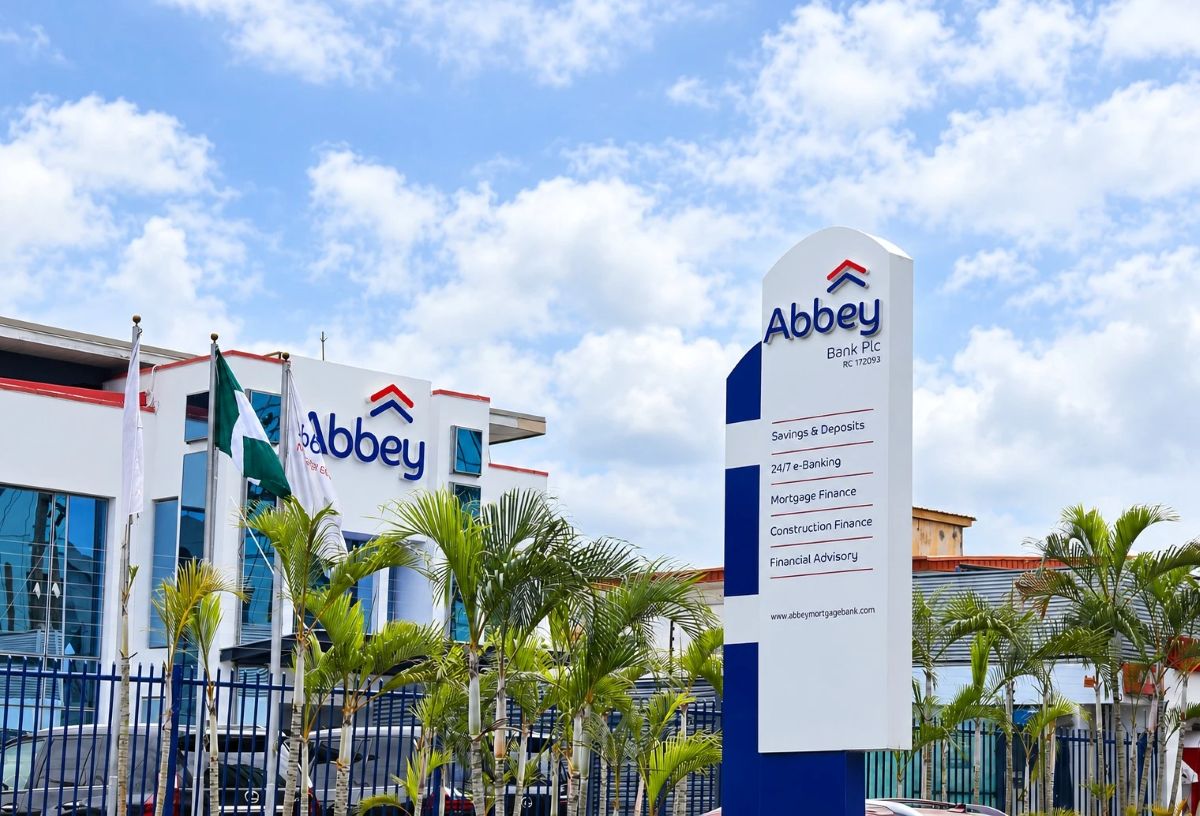
Abbey Bank Plc has retained its A3 short-term credit rating from Agusto & Co., alongside a BBB- rating and Stable Outlook, reflecting its improved capitalisation and strong liquidity position as disclosed in the latest rating affirmation by Agusto & Co. obtained by Nairametrics on Thursday, October 29, 2026.
The rating affirmation by Agusto & Co. stated that the bank’s strengthened financial position, expanding franchise and growing earnings diversification are expected to support its credit profile and capacity to meet short-term obligations.
The affirmation comes as Abbey Bank, formerly Abbey Mortgage Bank Plc, prepares to transition from a national mortgage bank into a regional commercial bank following approval from the Central Bank of Nigeria (CBN) in June 2026.
Abbey Bank maintained a strong liquidity position, with liquid assets of N148 billion representing approximately 89% of its N166 billion total assets as of December 31, 2025.
At the time, its non-performing loan ratio had declined to 8.1% as of July 2025 from 13.5% in December 2023, while its core capital ratio stood at 27.8%.
The latest decline in non-performing loans, alongside the bank’s substantial liquidity buffers, supports its strengthened credit profile.
Abbey Bank’s N64.5 billion equity raise is expected to strengthen its capital base and support its transition into regional commercial banking.
The bank received regulatory approval for the capital raise in August 2026, following shareholders’ approval of a private placement and additional fundraising plans.
The bank expects its earnings base to become more diversified as it develops activities in construction lending, fixed-income trading, foreign currency transactions and trade finance.
These developments form part of its strategy to strengthen profitability while maintaining prudent risk management and financial discipline.
Abbey Bank plans to commence regional commercial banking operations in November 2026, following the CBN’s approval of its licence transition in June.
The planned expansion will cover the South-West, South-South and North-West regions, alongside the Federal Capital Territory, broadening the bank’s operations beyond its traditional mortgage banking activities.
The transition represents a significant development for Abbey Bank as it seeks to expand its franchise and strengthen its earnings capacity. Its strengthened capital position and improved asset quality provide a foundation for the planned commercial banking operations.
However, the next important tests will be the November launch and how effectively the bank deploys its additional capital into loan growth and new revenue streams.