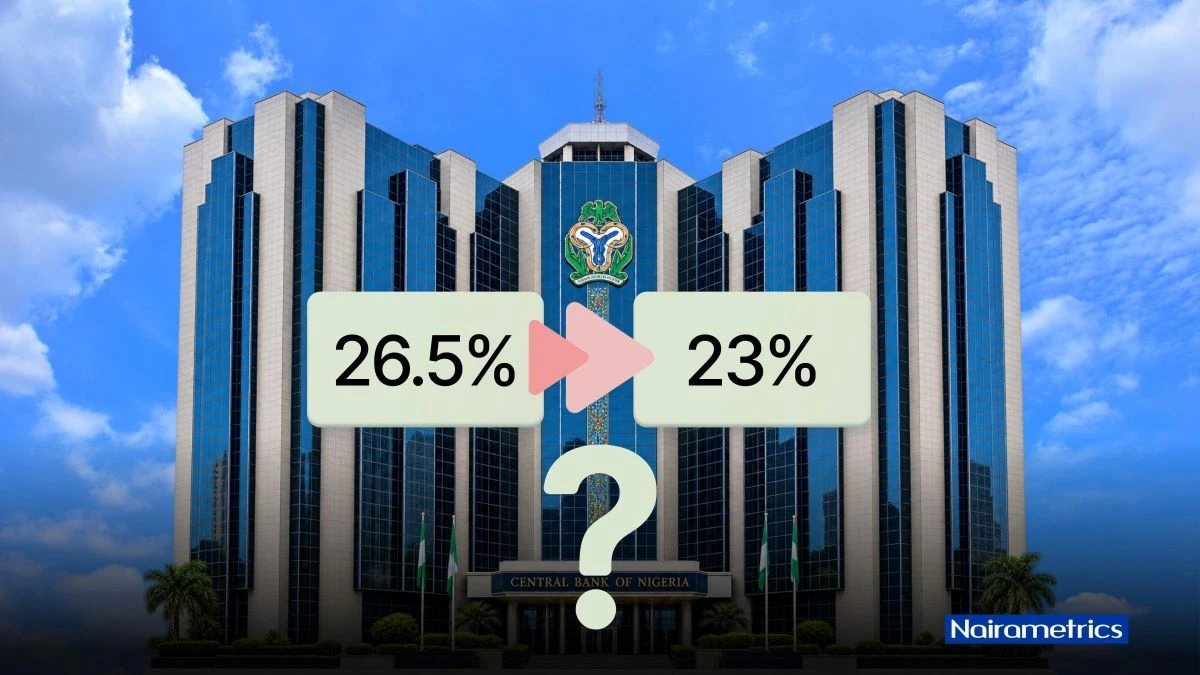
The Central Bank of Nigeria’s decision to cut its Monetary Policy Rate (MPR) to 23% marks a major shift in the country’s interest-rate environment, with implications for bond prices, mutual funds, pension portfolios and investors whose returns are linked to fixed-income and equity markets.
The Monetary Policy Committee (MPC), at its 307th meeting on September 22, 2026, reduced the benchmark rate by 350 basis points from 26.5% to 23%, its first MPR adjustment since February.
The decision comes as Treasury bill yields have already started moving lower, while inflation has continued to moderate and the investment space shifts away from the exceptionally high-yield fixed-income environment of much of 2024 and 2025.
For mutual funds and pension funds, the rate cut could mark the beginning of another portfolio transition cycle, where fixed-income returns may moderate while equities become increasingly relevant to maintaining overall portfolio performance.
Even before the MPR was reduced, the fixed-income market had begun pricing a lower interest-rate environment, with Treasury bill yields declining despite strong investor demand for government securities.
At the September 9 Treasury bill auction, the stop rate on the 364-day bill fell to 16.62%, from 16.84% on September 2 and 17.59% on August 12.
Money-market funds are particularly sensitive to changes in short-term interest rates because a significant portion of their portfolios are invested in Treasury bills, commercial papers and other short-duration fixed-income securities.
An implication of lower interest rates is that existing bonds become more valuable. Bond prices generally move inversely to market yields.
Recent FGN bond auction results provide evidence of the movement in the longer end of the fixed-income market.
Lower interest rates generally improve the relative attractiveness of equities.
The implications for pension funds are broader because Pension Fund Administrators (PFAs) manage diversified portfolios across government securities, equities, money-market instruments and other approved asset classes.
PenCom data showed that approximately N17.40 trillion of pension fund assets were invested in FGN securities as of June 2026.
Samuel Oyekanmi, Head, Research & Insights, Norrenberger, said pressure on Treasury bill yields could become more pronounced if the easing cycle continues following the reduction in the MPR to 23%.
According to Oyekanmi, fixed-income markets had already begun pricing in the possibility of rate cuts before the MPC announcement, meaning some of the adjustment in yields may already have occurred.
Nathanael Disu, Equity Research Analyst, Afrinvest, also highlighted the potential implications for equities.
According to Disu, the CBN’s 350-basis-point rate cut could support demand for equities as investors reassess allocations between fixed-income securities and risk assets.
Disu noted that the NGX recorded a strong performance in 2026, with the market’s year-to-date return around 61%.
He also pointed to Nigeria’s inclusion in the FTSE Russell Frontier Market Index as another factor that could influence market flows, alongside the expected release of first-half earnings by major banks.
Kehinde Jones, Head, Research and Strategy at Anchoria Capital Group, said the 350-basis-point reduction in the MPR, from 26.5% to 23%, represents a significant shift in the interest-rate environment, particularly as inflation continues to moderate and economic activity improves.
Jones added that the lower-yield environment could also influence portfolio allocation as investors reassess the relative attractiveness of different asset classes.
On equities, Jones said the lower MPR could support investor interest as market participants look for returns outside traditional fixed-income instruments.
He added that lower borrowing costs could support corporate earnings and valuations, particularly for consumer, industrial and oil and gas companies, if the reduction in the policy rate eventually translates into lower lending rates.
However, Jones cautioned that the impact would depend on the speed and extent of monetary-policy transmission.
He also noted that after the strong gains recorded by the equities market, stock selection and valuation would remain important considerations for investors.
For retail investors, an MPR of 23% does not automatically translate into a 23% investment return.
The more important variables are the direction of Treasury bill yields, bond yields and equity prices, as well as how individual investment portfolios are positioned for the changing rate environment.
The same 350-basis-point cut can produce very different outcomes for a money-market fund, a bond fund, an equity fund, and a pension portfolio.
And that is why the next phase of Nigeria’s monetary easing cycle may be less about headline interest rates and more about how effectively fund managers navigate the changing relationship between yields, bond prices, equities and inflation.