Daraju Industries Limited has opened an offer of up to N10 billion Series 4 Commercial Paper under its N50 billion Commercial Paper Programme.
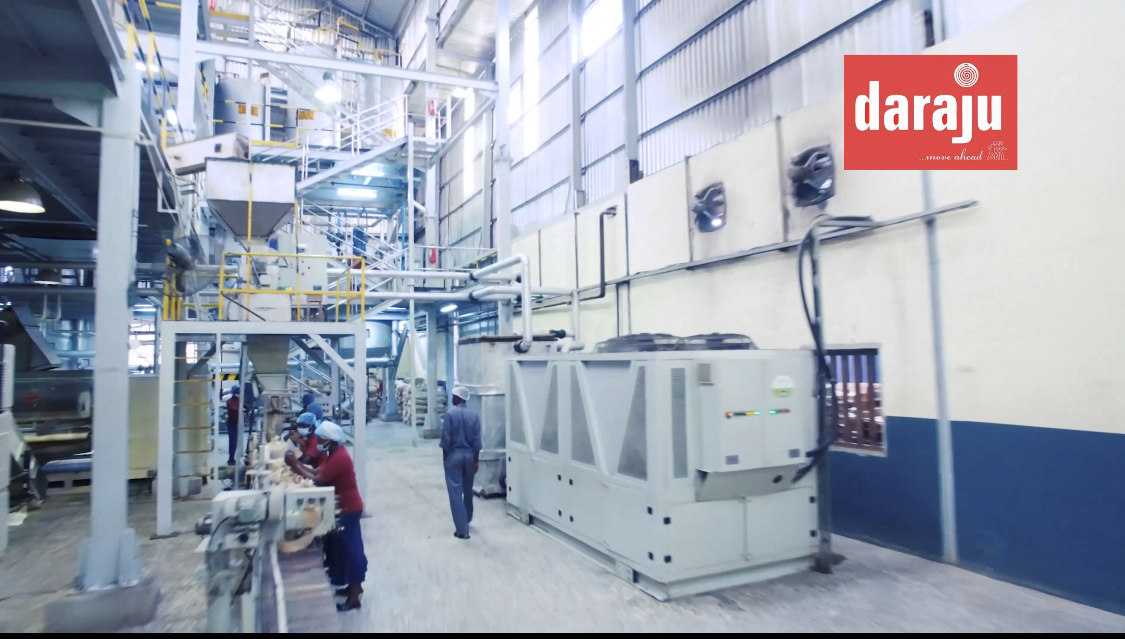
The Lagos-based manufacturer, which began operations in 1988 and produces MYMY toothpaste, soaps and detergents, has been using the market to raise money for its short-term working capital needs
This offer carries an implied annual yield of 23%, meaning investors who hold the paper until maturity would earn about 23% on the amount invested, provided Daraju repays in full.
The offer opened on Thursday, October 8, 2026, and closes on Friday, October 16, 2026. The paper runs for 364 days.
The issuance follows Daraju’s offer of up to N5 billion Series 3 commercial paper in February 2026, which also carried a 364-day tenor and a 23% implied annual yield.
For the latest offer, proceeds will support short-term funding needs. This provides money for the company’s working capital for the day-to-day funding required to keep its manufacturing and distribution business running.
For a manufacturer such as Daraju, these needs include buying raw materials, producing goods, and holding stock before customer payments are received.
Investors earn income by purchasing the paper below its repayment value and receiving that value at maturity.
The implied annual yield of 23% measures the income against the amount paid upfront.
Repayment is scheduled for October 18, 2027, following issuance on October 19, 2026. Investors receive their money at maturity, subject to Daraju meeting its obligation.
Daraju’s 23% yield offers 4.17 percentage points above the comparable Treasury bill yield of 18.83%. This translates to approximately N208,000 extra on N5 million actually invested over 364 days, before taxes and fees, assuming full repayment.
Whether that sufficiently rewards investors depends on Daraju’s ability to repay.
The company has repeatedly issued CP, and its accounts record substantial aggregate debt repayments. However, these do not establish that every matured CP series was repaid on time.
Renewed sales growth, better production efficiency, and cheaper funding could improve coverage.
However, finance costs rose 53% in 2025, alongside a 21% increase in borrowings and import finance. Further borrowing or higher input costs could absorb operating improvements.
The balance sheet remains stretched.
Borrowings of N60.22 billion were 13.7 times equity, down from 18.7 times because equity strengthened, although debt increased.
The premium therefore warrants caution. Improving margins offer encouragement, but verified CP redemptions, funding for upcoming maturities and stronger cash generation would make the additional return more persuasive.
The paper offers a 23% implied annual yield over 364 days, with income received through repayment at maturity.
Daraju’s established brands and improving production margins support its business, but borrowing costs leave limited room for setbacks.
Investors should compare the additional income with Treasury bills of a similar tenor, allowing for applicable taxes, fees and differences in liquidity.
Those needing their money before maturity should confirm whether they can sell the paper and at what potential cost.
However, the public sources reviewed did not provide verified evidence of delayed CP payments.
The extra yield should therefore be weighed against Daraju’s ability to generate cash and secure funding throughout the investment period.