When the Central Bank of Nigeria (CBN) announced a reduction in the benchmark interest rate to 23 per cent at its September monetary policy meeting, attention quickly shifted to what the decision meant for inflation, borrowing costs, businesses, investors and the wider economy.
For many market watchers, the outcome of a Monetary Policy Committee (MPC) meeting is often reduced to a single number: whether the Monetary Policy Rate (MPR) has been raised, lowered or left unchanged.
But behind that announcement lies a process involving economic data, individual assessments, scenario analysis, competing policy preferences, institutional checks and, ultimately, a vote.
The two-day meeting is the most visible part of a process that begins well before committee members gather around the table. By the time the governor addresses journalists and announces the outcome, members have already examined the available evidence, considered possible economic scenarios and developed their individual positions on the policy choices before them.
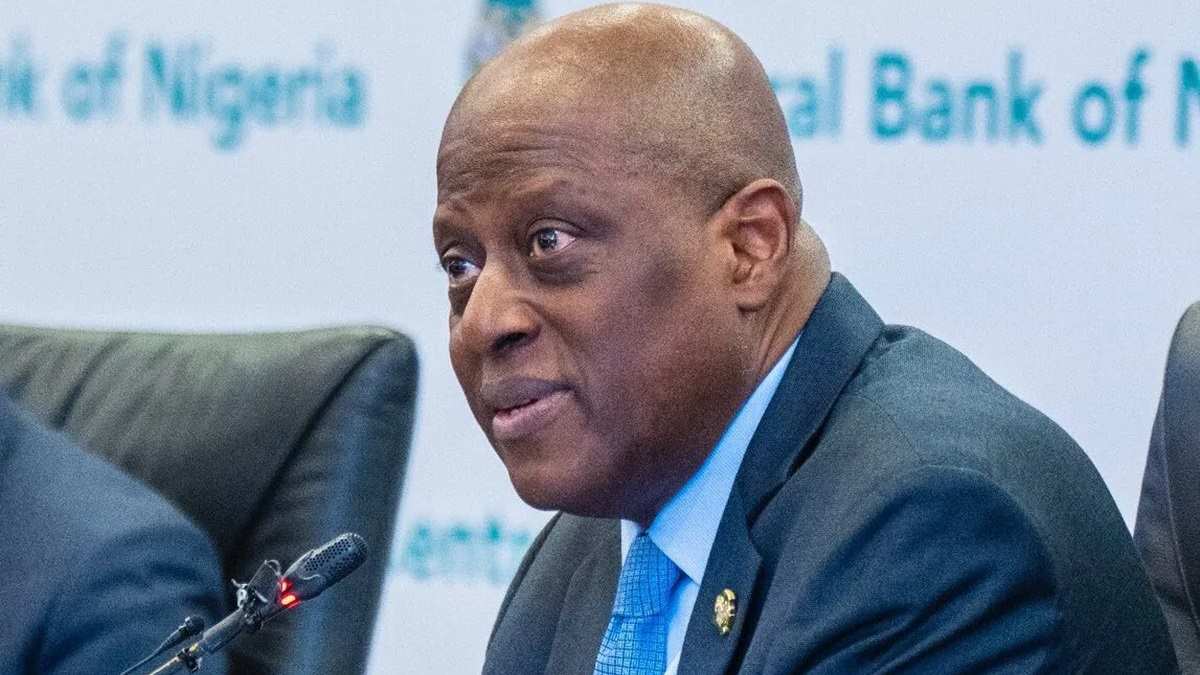
The workings of this process were brought into focus by CBN Governor Olayemi Cardoso during a panel discussion at the 2026 Annual Meetings of the International Monetary Fund (IMF) and the World Bank in Bangkok, Thailand.
Speaking on a panel titled “How Central Banks Decide: Committee Decision Making and Communication in an Era of Uncertainty,” Cardoso offered insight into how Nigeria’s monetary policymakers prepare for meetings, manage disagreements, challenge established assumptions and arrive at decisions with consequences extending far beyond the banking system.
The panel, moderated by IMF First Deputy Managing Director Dan Katz, also featured Banque de France Governor Emmanuel Moulin and Chairman of the Governing Board of the Swiss National Bank Martin Schlegel. Discussions examined how central banks organise collective decision-making at a time when economic uncertainty, inflationary pressures and changing market conditions have complicated the task of setting monetary policy.
For Nigeria, where monetary policy decisions influence the cost of credit, investment decisions, exchange-rate expectations, inflation and household purchasing power, the process is particularly consequential.
The MPR is not simply an administrative figure announced after a meeting. It is a policy instrument through which the CBN attempts to influence financial conditions and steer the economy towards price stability.
A higher rate generally makes borrowing more expensive and can help moderate demand and inflationary pressures, although its effects depend on how monetary policy is transmitted through the financial system. A lower rate can ease financing conditions and support economic activity, but its implications also depend on inflation expectations, liquidity conditions and the broader economic environment.
Determining the appropriate direction requires policymakers to assess competing risks. Tightening policy too aggressively can constrain businesses and investment, while easing too quickly can undermine efforts to contain inflation and stabilise expectations.
Against this backdrop, the structure and deliberations of the MPC become important.
It is gathered that Nigeria’s MPC comprises 12 members: seven internal members and five external members.
The composition is significant because it brings together officials who work within the central bank and independent members who can approach the same economic questions from outside the institution.
For Cardoso, the presence of external members is an important safeguard against groupthink, particularly given the economic circumstances in which the CBN has had to rebuild confidence in its policy framework.
“Fundamental to that was ensuring that the outside, independent members of the MPC were strong, well-recognised, independent-minded people, so that the risk of groupthink was significantly reduced,” he said.
Groupthink occurs when members of a decision-making body become too comfortable with a prevailing institutional position, discouraging dissenting opinions or alternative interpretations of the evidence.
In monetary policymaking, this can be costly. If committee members accept a common diagnosis without adequately testing it, they may overlook emerging risks, misjudge inflationary pressures or underestimate the consequences of a policy decision.
The inclusion of external members is intended to make such outcomes less likely by bringing different professional experiences, analytical approaches and perspectives into the discussion.
Internal members possess detailed knowledge of the CBN’s operations, policy tools and economic assessments. External members, however, may be better positioned to question assumptions that have become familiar within the institution.
Cardoso acknowledged this difference, noting that internal members can sometimes become attached to established approaches because of their daily exposure to the same institutional practices.
“There’s a tendency at times for the internals to perhaps hold on to data practices that they see every day,” he said.
External members can challenge those practices, ask whether the assumptions behind them remain valid and introduce alternative ways of interpreting the available evidence.
Their value, therefore, is not merely in adding numbers to the committee. It lies in strengthening the quality of deliberations by ensuring that policy arguments are subjected to scrutiny from different perspectives.
However, diversity of opinion alone does not guarantee better decisions. Members must have access to reliable information, sufficient time to examine the evidence and the freedom to express their views without being pressured to conform to a preferred outcome.
This is why the preparation preceding MPC meetings is as important as the discussions themselves.
The work begins before members enter the meeting room
Contrary to the impression that monetary policy decisions are shaped entirely during the two-day meeting, Cardoso explained that committee members begin their assessments well in advance.
They receive relevant economic data before the meeting, allowing them to study the information, examine developments in the economy and determine what policy response they consider appropriate.
This preparation is intended to ensure that members do not arrive at the meeting relying exclusively on presentations or arguments made by the governor or other senior officials.
Instead, each member is expected to develop an independent position after examining the evidence.
The data provide the starting point, but the analysis extends beyond simply reviewing headline figures.
Members can interrogate the information, seek clarification from the MPC secretariat and conduct scenario analysis to assess the possible implications of alternative policy choices.
Such analysis is particularly important when the economic outlook is uncertain. Policymakers must consider not only what is happening at the time of the meeting but also how inflation, output, exchange-rate developments and financial conditions might respond to different policy decisions.
For example, a decision to maintain a restrictive monetary stance may help preserve pressure against inflation, but it could also increase financing costs for businesses already struggling with expensive credit.
Conversely, lowering rates may improve the prospects for borrowing and investment, but policymakers must assess whether the move could weaken the fight against inflation or affect confidence in the domestic currency.
The committee must weigh these considerations against the available evidence rather than assume that one policy direction is automatically preferable.
Cardoso said the CBN has a strong secretariat to provide the technical support members require during this process.
The secretariat gives members access to information and analysis and provides a channel through which they can ask questions about the data and the assumptions underpinning policy assessments.
Members can also undertake what-if analysis and scenario assessments before the formal deliberations begin.
The arrangement gives them the opportunity to consider the consequences of different choices privately before defending their positions before colleagues.
Cardoso was emphatic that he does not hold preliminary meetings with internal members to agree on the outcome before the formal MPC meeting.
“There’s never a case where I have meetings with internals and come to a conclusion on the MPC meetings before we go there. I don’t do that,” he said.
He explained that the data are made available in advance and members are free to interrogate them and develop their own views.
“I give all the data out in advance. People interrogate them. They have a very strong secretariat, so you can ask questions of the secretariat. You can do what-if analysis, your scenario analysis, and then you keep it to yourself. And then, when we get into the meeting, the real job starts.”
This approach is designed to preserve the distinction between the governor’s leadership of the institution and the collective responsibility of the committee to determine monetary policy.
Although the governor chairs the MPC and plays a central role in explaining its decisions, the committee’s deliberations are intended to allow members to assess the evidence independently before arriving at a collective outcome.
Why external members matter beyond representation
The five external members occupy an important position in this arrangement because they are expected to contribute meaningfully to the committee’s work rather than serve as passive participants.
Their independence, however, must be supported by access to the information and resources needed to understand the issues before the committee.
Cardoso said the CBN provides resources to external members and allows them, where necessary, to engage specialists outside the institution.
This is important because external members may not have the same day-to-day access to the CBN’s internal analytical processes as officials working within the bank.
Without adequate preparation and technical support, their formal inclusion could fail to translate into substantive participation.
The CBN also organises retreats and other engagements outside the formal MPC meeting cycle. These may involve experts from other central banks, exposing members to different experiences and approaches to monetary policymaking.
Multi-stakeholder engagements provide additional opportunities for members to hear perspectives from different participants in the economy.
Such engagements matter because the effects of monetary policy are not confined to the financial markets. Businesses, manufacturers, households, investors and financial institutions all experience the consequences of interest-rate decisions in different ways.
Manufacturers, for instance, may be concerned about the cost of financing working capital and expanding production. Banks must consider the effects of interest rates on lending, deposits and credit risk. Investors assess how monetary policy affects the attractiveness of financial assets, while households contend with the consequences of inflation and borrowing costs.
Although the MPC must make decisions in pursuit of its policy objectives rather than satisfy every stakeholder, understanding these different perspectives can help members evaluate how policy changes may affect the wider economy.
Cardoso also said external members are involved from the beginning in Nigeria’s transition towards inflation targeting.
The significance of this approach is that members are not introduced to a new policy framework only when decisions are about to be taken. Their participation begins early enough for them to understand the objectives, assumptions and analytical requirements associated with the transition.
A common understanding of the framework can improve the quality of deliberations, even when members disagree about the appropriate policy response.
Inside the meeting: Finding common ground before confronting differences
Once the formal meeting begins, the responsibility shifts from individual preparation to collective deliberation.
The governor, as chairman, must steer discussions towards the issues that matter and ensure that members’ contributions help the committee reach a decision.
Cardoso described a three-stage approach: establish what members agree on, identify the areas where they disagree and then vote.
The sequence is intended to prevent discussions from becoming bogged down in differences that may be less important than the central economic problem confronting the committee.
“If you don’t do that and you take on the things you disagree on first, you may end up spending so much time on what could arguably be relative minutiae,” he said.
The approach recognises that members can disagree about the appropriate response while sharing a common understanding of the problem that needs to be addressed.
For example, members may agree that inflationary pressures remain a concern but differ on whether interest rates should be increased, maintained or reduced. They may also disagree about the speed at which monetary policy is affecting economic activity or the extent to which existing policy measures are delivering the intended results.
Establishing the areas of agreement first helps define the central questions before the committee considers the competing policy options.
It also creates a clearer basis for assessing disagreements. Rather than allowing the meeting to become a contest between opposing positions, members can examine why their interpretations differ and what the evidence suggests about the consequences of each option.
This is particularly relevant in periods of uncertainty, when economic indicators may point in different directions or when the effects of earlier policy decisions have yet to become fully apparent.
The transmission problem at the heart of monetary policy
Cardoso cited the MPC’s deliberations on the monetary policy transmission mechanism as an example of how establishing common ground can improve discussions.
The transmission mechanism describes how changes in monetary policy influence the wider economy through channels such as bank lending rates, credit availability, asset prices, exchange-rate expectations and aggregate demand.
In theory, an increase in the policy rate should influence financial conditions, affect borrowing and spending decisions and, over time, help moderate inflationary pressures.
However, the strength and speed of this process depend on the structure of the financial system and the conditions prevailing in the economy.
If changes in the policy rate are not transmitted effectively to lending and deposit rates, the central bank may find that its decisions do not produce the intended effects across the economy.
Similarly, the impact of monetary tightening may vary between businesses with access to different sources of financing and households with different levels of exposure to credit.
Cardoso said members entered the relevant deliberations amid considerable uncertainty but reached a common understanding that the transmission mechanism was not functioning properly and needed to be corrected.
Once that shared diagnosis had been established, members could concentrate on the appropriate response instead of becoming trapped in prolonged disagreements about the nature of the problem.
The example illustrates a broader challenge for monetary policymakers: determining the appropriate policy rate is only one part of the task. The central bank must also understand how its decisions travel through the financial system and affect the economic activities they are intended to influence.
For Nigeria, this question is important because the effectiveness of monetary policy depends partly on how financial institutions respond to changes in the CBN’s policy stance and how those changes affect businesses and households.
A policy decision may be technically sound but deliver weaker-than-expected results if the transmission channels are impaired.
This makes the committee’s assessment of the transmission mechanism essential to understanding not only what decision to take but also whether the existing policy framework is working as intended.
After examining the available evidence, considering alternative scenarios and debating the implications of different options, the MPC votes on its policy decision.
The vote marks the point at which individual assessments are translated into a collective outcome.
Members may agree on the direction of policy but differ on the magnitude or timing of a change. Others may prefer to maintain the existing stance because they believe the available evidence does not yet justify a shift.
Such differences are not necessarily signs of institutional weakness. They can reflect the uncertainty surrounding economic forecasts and the competing risks associated with monetary policy.
Indeed, disagreement can strengthen decision-making when it forces members to defend their assumptions, explain their reasoning and consider arguments they might otherwise overlook.
The important question is whether the process allows those differences to be expressed and evaluated before the committee reaches its decision.
Cardoso’s account suggests that the CBN seeks to preserve this space for debate by allowing members to prepare independently, challenge assumptions during deliberations and vote after considering the competing arguments.
The decision ultimately announced by the governor is therefore the outcome of a collective process, rather than simply a policy instruction issued by the head of the central bank.
However, the quality of that process cannot be judged solely by whether members reach a decision. Its effectiveness also depends on the quality of the evidence, the seriousness of the debate, the independence of members and the clarity with which the decision is subsequently explained.
The MPC’s work does not end with the vote, Cardoso said members’ personal statements provide additional insight into their individual positions and the reasoning behind them.
He explained that he makes a point of reading every member’s statement, including those from members whose views may differ from the final decision.
“I make it a point of duty to read every person’s personal statement, and these are not people who withhold what they think,” he said.
These statements serve an important purpose in a system where collective decisions can conceal differences in the reasoning that produced them.
An announcement that the committee has reduced, increased or retained the MPR tells the public what the CBN has decided. It does not, by itself, explain how individual members assessed the risks, which economic indicators they considered most important or why they preferred one policy option over another.
They provide an opportunity for members to explain their positions and reveal the range of views that informed the committee’s deliberations.
For the governor, reading those statements also offers an opportunity to understand arguments that may need further consideration at subsequent meetings.
This is particularly important because monetary policymaking is a continuing process. Decisions made at one meeting influence the economic conditions that members assess at the next, while new data may require the committee to revisit earlier assumptions.
The statements can therefore contribute to institutional learning by preserving the reasoning behind individual positions rather than allowing the final decision to become the only public record of the meeting’s outcome.
They also provide markets and other observers with a more detailed basis for assessing the committee’s thinking.
Investors and businesses closely monitor monetary policy because changes in the policy outlook can influence asset valuations, financing costs and investment decisions. Greater insight into members’ reasoning can help them understand the considerations that may shape future decisions, although it cannot eliminate uncertainty about the committee’s next move.
At the end of the meeting, the CBN governor communicates the committee’s decision to the media and the public, while members’ published statements provide additional insight into their individual positions.
This arrangement seeks to balance the need for a clear institutional message with transparency about the range of views within the committee.
Cardoso said transparency is central to building an MPC whose decisions command public and market confidence. He also noted that external members sometimes challenge the institution to disclose information when they consider existing public disclosure inadequate.
When businesses and investors understand the central bank’s objectives and the reasoning behind its decisions, they have a better basis for assessing the likely direction of policy.
Conversely, uncertainty about the central bank’s thinking can complicate decisions on borrowing, investment, pricing and portfolio allocation.
Transparency does not require policymakers to agree on every issue or eliminate uncertainty from their communication. Rather, it requires the institution to explain its decisions clearly and provide sufficient information for the public to understand the reasoning behind them.
The publication of individual statements can support this objective by showing that the committee’s decisions emerge from deliberation and that different positions can be expressed within the process.
Nevertheless, transparency is most useful when disclosures are timely, understandable and sufficiently detailed to explain the economic considerations behind a decision. Information that is technically available but difficult to interpret may do little to improve public understanding.
For the CBN, the challenge is therefore not simply to announce policy decisions but to communicate the reasons for them in a manner that strengthens confidence in the institution’s objectives and method.
The MPC’s internal procedures may appear distant from the daily concerns of ordinary Nigerians, but the decisions reached by the committee have consequences for the wider economy.
When the CBN changes the MPR, the effects can spread through financial markets, bank lending conditions, investment decisions and expectations about inflation and the exchange rate.
For businesses, the implications include the cost and availability of credit. Companies that depend on bank financing may have to reassess working-capital requirements, expansion plans and the prices of goods and services.
For households, monetary policy can influence borrowing costs, savings returns and the broader economic conditions that affect purchasing power and employment.
Investors, meanwhile, assess changes in interest rates when deciding how to allocate funds between equities, fixed-income securities, deposits and other assets.
These effects do not occur uniformly or immediately. The transmission of monetary policy takes time, and outcomes depend on a range of domestic and external factors.
This makes the MPC’s deliberations important beyond the financial-market reaction to its announcement.
A well-reasoned decision requires members to consider the competing risks associated with inflation, economic activity and financial conditions. It also requires them to assess whether earlier policy decisions are producing the expected results.
The committee’s structure, preparation and debate are therefore part of a wider effort to ensure that monetary policy is based on evidence and that the implications of alternative choices are properly considered.
The experience described by Cardoso reflects a fundamental problem facing central banks: monetary policy must often be set before policymakers have complete information about the economy.
Inflation figures describe developments over a particular period, while the effects of policy changes may take months to emerge. Economic forecasts can change as new information becomes available, and external shocks can alter the outlook between meetings.
Under these conditions, no single economic indicator can provide a complete answer to the question of whether interest rates should rise, fall or remain unchanged.
Committee members must interpret the available evidence, assess the reliability of their assumptions and consider how different policy choices could affect the economy under alternative scenarios.
The quality of the decision depends partly on how effectively the committee manages these uncertainties.
Cardoso’s description highlights several elements of the CBN’s approach: advance access to data, independent preparation, technical support from the secretariat, participation by external members, structured deliberations, voting and the publication of individual statements.
Together, these mechanisms are intended to make the process more rigorous and reduce the risk that decisions are driven by institutional habit or a narrow range of views.
Yet the existence of such procedures does not, on its own, establish whether a particular interest-rate decision is economically correct. That judgment also depends on the evidence available at the time, the consistency of the committee’s reasoning and the results that follow.
Ultimately, the MPC must be assessed both by the quality of its decision-making process and by how effectively its policies advance the CBN’s monetary policy objectives.
For Nigerians, the significance of the committee’s work lies not merely in the number announced after each meeting but in the reasoning, analysis and collective judgment behind it.
As Cardoso’s account of the MPC suggests, the decision announced at the end of two days is only the visible conclusion of a much longer exercise in economic assessment, debate and accountability.
We’ve got the edge. Get real-time reports, breaking scoops, and exclusive angles delivered straight to your phone. Don’t settle for stale news. Join THISTIMES on WhatsApp for 24/7 updates →
Join Our WhatsApp Channel